
What to Do After an Accident: A Step by Step Guide

A crash can turn an ordinary drive into a confusing, stressful mess in seconds. Even a minor accident can leave you shaken, unsure who to call, what to say, and what details matter later.
The best thing you can do is follow a simple order: get safe, get help, document what happened, and protect your health and records. This guide walks through the process after a car accident in the United States, from the first few minutes at the scene to the days that follow.
This article is for general information only. It is not legal, medical, or insurance advice. Rules vary by state, and serious accidents may require help from a doctor, attorney, or insurance professional.

Step 1. Get to safety and check for injuries
The first few minutes matter most. Before you think about damage, insurance, or who caused the crash, focus on safety.
If the vehicles are still in traffic and can be moved, pull over to a safe place nearby. Choose a shoulder, parking lot, side street, or another area away from moving vehicles. Turn on your hazard lights. If you have emergency triangles, flares, or cones, use them only if you can do so safely.
Then check yourself and others for injuries. Look for signs such as:
Pain in the head, neck, back, chest, or abdomen
Dizziness, confusion, or faintness
Bleeding, swelling, or numbness
Trouble breathing
Any injury involving a child, older adult, pedestrian, bicyclist, or motorcyclist
Call 911 right away if anyone may be injured, if a vehicle is blocking traffic, if there is leaking fuel, if a driver appears impaired, or if you feel unsafe.
If someone is seriously hurt, do not move them unless they are in immediate danger, such as from fire or traffic. Wait for emergency responders and follow their instructions.
Even when damage looks minor, the scene can still be risky. Other drivers may not see stopped vehicles in time. Keep everyone as far from traffic as possible.
Step 2. Call the police when the situation calls for it
Not every small bump requires a police response, but many accidents do. State laws differ, and some require a report when there are injuries, deaths, hit-and-runs, suspected impairment, or property damage above a certain amount.
When in doubt, call the non-emergency police number or 911 and explain what happened. Dispatchers can tell you whether an officer should respond.
A police report can help later because it creates an official record. It may include:
The date, time, and location
Driver and vehicle details
Insurance information
Statements from drivers or witnesses
Road and weather conditions
A diagram or summary of the crash
Any citations issued at the scene
If an officer comes to the scene, ask how to get a copy of the report. You may need the report number, the officer’s name, or the agency name.
Be calm and factual when speaking with police. Say what you saw and remember, but do not guess. If you are unsure about speed, distance, or timing, it is fine to say so.
Step 3. Exchange information with the other driver
Once everyone is safe and help is on the way, exchange basic information with the other driver. Keep the conversation short and polite. You do not need to argue about fault at the scene.
Collect the following details:
Information to collect | Why it matters |
Full name and phone number | Helps with insurance follow-up |
Driver’s license number | Confirms identity |
License plate number | Identifies the vehicle |
Vehicle make, model, and color | Helps document the crash |
Insurance company and policy number | Needed for claims |
Vehicle owner name, if different from the driver | Important when the driver does not own the car |
If the other person refuses to share information, do not escalate the situation. Stay safe and wait for police if they are responding. If you can safely record the license plate and vehicle description, do so.
Avoid saying things like “I’m sorry, it was my fault,” even if you are trying to be polite. A crash can involve facts you do not know yet, such as a traffic signal issue, poor visibility, speeding, distraction, vehicle defects, or another driver’s actions. Stick to facts.
Step 4. Document the accident scene
Good documentation can make the claims process much easier. If you are physically able and it is safe, take photos and videos before the vehicles are moved. If the cars must be moved for safety, take photos after moving them too.
Capture wide shots and close-ups. The goal is to show both the overall scene and the details.
Take photos of:
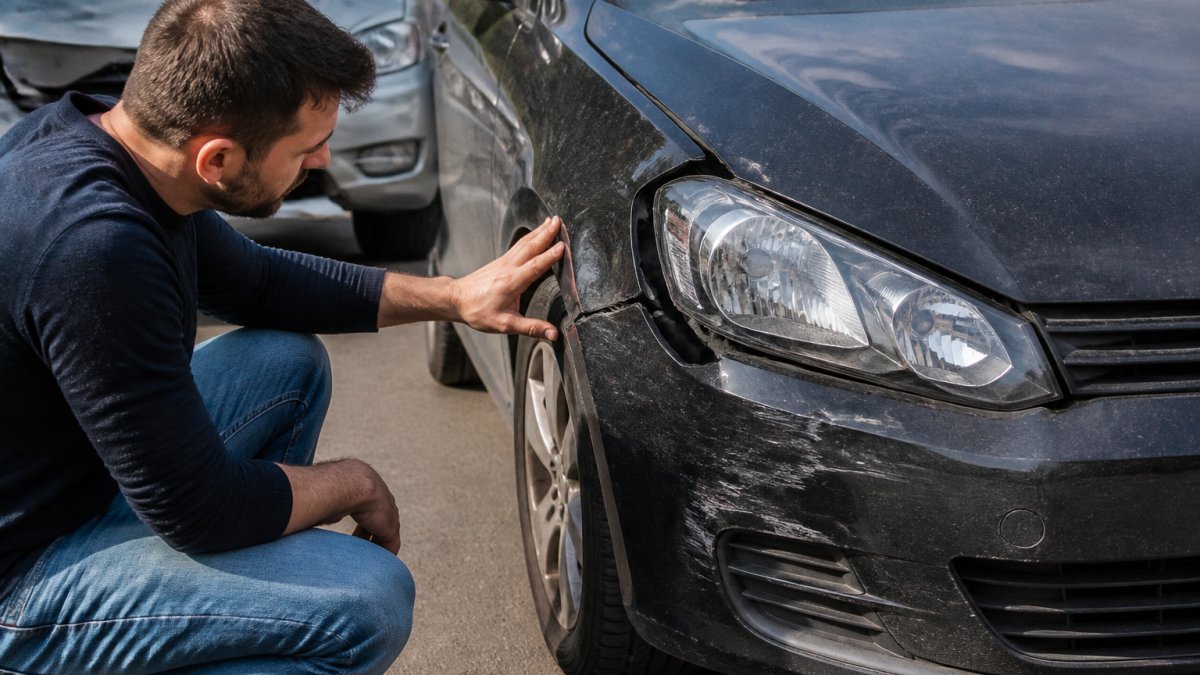
Vehicle damage from multiple angles
The position of the vehicles
License plates
Skid marks, broken glass, and debris
Traffic lights, stop signs, lane markings, and road signs
Weather, lighting, and road conditions
Nearby driveways, intersections, or parking lot exits
Visible injuries, if appropriate and respectful
Damage to guardrails, fences, signs, or other property
Also write down quick notes while the details are fresh. Include the time, location, direction of travel, traffic conditions, and what happened right before impact.
If there are witnesses, ask for their name and contact information. A neutral witness can be helpful when drivers remember the event differently.

Step 5. Get medical attention even if you feel fine
Adrenaline can hide pain after a crash. Some symptoms show up hours or days later, especially soft tissue injuries, concussions, and back or neck pain.
Seek emergency care right away for serious symptoms. For less obvious pain, consider calling your doctor, visiting urgent care, or following the advice of emergency responders.
Watch for symptoms such as:
Headache that gets worse
Neck or back pain
Nausea or vomiting
Dizziness or balance problems
Confusion, memory gaps, or trouble focusing
Numbness or tingling
Chest pain or shortness of breath
Abdominal pain or swelling
Medical records can also matter for insurance claims. They show when symptoms were reported and what care was recommended. If you delay treatment, an insurer may question whether the injury came from the accident.
Follow the care plan you receive. Keep copies of discharge papers, prescriptions, referrals, physical therapy instructions, and bills. If symptoms change, document that too.
Step 6. Notify your insurance company
Contact your insurance company as soon as reasonably possible. Many policies require prompt notice after an accident. You do not need to have every detail ready, but you should report the basic facts.
Before calling, gather what you have:
Your policy number
Date, time, and location of the accident
Other driver’s information
Police report number, if available
Photos and videos
Names of witnesses
A short factual description of what happened
When you speak with an adjuster, be accurate and brief. Do not exaggerate, guess, or give opinions about injuries or fault. If you are unsure, say so.
Ask questions about your coverage. Depending on your policy and state, you may need to understand:
Collision coverage
Liability coverage
Uninsured or underinsured motorist coverage
Medical payments coverage
Personal injury protection
Rental car coverage
Deductibles
Repair shop options
You may also hear from the other driver’s insurance company. Be careful. Their job is to evaluate the claim for their insured, not to guide you personally. You can provide basic facts, but you do not have to give a recorded statement without understanding the impact. If injuries are involved or fault is disputed, consider getting legal advice before making detailed statements.
Step 7. Start a file for every accident-related record
A car accident creates paperwork quickly. Keeping everything in one place can save time and reduce stress.
Create a folder on your phone, computer, or in a physical file. Save copies of:
Photos and videos from the scene
Police report information
Insurance claim numbers
Repair estimates
Towing and storage receipts
Rental car receipts
Medical bills and records
Prescription receipts
Notes about missed work
Messages from insurers
Names and phone numbers of everyone involved
It also helps to keep a simple accident journal. Write short entries about symptoms, doctor visits, vehicle issues, and claim updates. Date each entry.
For example:
Date | What happened |
May 4 | Reported accident to insurer and received claim number |
May 5 | Neck pain started, called primary care doctor |
May 7 | Vehicle inspected at repair shop |
May 10 | Received police report copy |
You do not need long entries. The point is to create a clear timeline.
Step 8. Handle vehicle repairs carefully
After the claim is opened, your insurer may send an adjuster, ask for photos, or refer you to repair shops. You may also be able to choose your own repair shop, depending on your policy and state rules.
Before authorizing repairs, ask:
What damage is included in the estimate?
Could hidden damage appear after the shop starts work?
How long will repairs take?
Will replacement parts be original equipment, aftermarket, used, or rebuilt?
Is the work guaranteed?
Who pays the shop directly?
Will you owe a deductible?
Do you have rental coverage while repairs are underway?
If your car is not safe to drive, do not drive it. Damage to lights, tires, steering, brakes, airbags, or frame components can create danger even if the car still starts.
If the insurer declares the vehicle a total loss, ask how they calculated the value. Review the vehicle details, mileage, trim, condition, and comparable vehicles used. Mistakes can happen, and you can ask for clarification.
Step 9. Be careful with settlement offers
Insurance claims can move fast, especially when another insurer wants to close the file. A quick settlement may seem helpful, but it can create problems if your injuries or costs are not fully known yet.
Before accepting money or signing a release, make sure you understand what it covers. A release may prevent you from asking for more later, even if medical bills increase or symptoms continue.
Be especially cautious if:
You were injured
Symptoms are still changing
You missed work
The accident involved a commercial vehicle
Fault is disputed
The other driver was uninsured or underinsured
A child was injured
There were multiple vehicles
You feel pressured to decide quickly
For a minor property damage claim, the process may be simple. For injuries or major losses, it may be wise to speak with an attorney in your state before signing anything.
Step 10. Know when to ask for help
Some accidents can be handled with a few phone calls and repair estimates. Others become complicated quickly.
Consider getting professional help if the accident involves serious injuries, long-term pain, disputed fault, denied coverage, a hit-and-run, a drunk or distracted driver, or pressure from an insurance company.
You may also need support if the crash affects your daily life. Transportation problems, medical appointments, missed work, and stress can pile up. Ask family, friends, your medical provider, or your insurer about practical next steps.
The key is to avoid making rushed decisions while you are still processing what happened.
A quick checklist for the first 24 hours
Use this checklist as a simple reminder if you are trying to get organized after a crash.
Move to safety and turn on hazard lights.
Check for injuries and call 911 when needed.
Exchange contact, vehicle, and insurance information.
Take photos and videos of the scene.
Get witness contact information.
Ask how to obtain the police report.
Seek medical care if you are hurt or unsure.
Notify your insurance company.
Save receipts, records, and claim numbers.
Avoid admitting fault or signing anything you do not understand.
What to remember after an accident
The most important steps after an accident are simple, but they are easy to forget in the moment. Protect people first. Call for help when needed. Gather clear information. Get medical care. Report the crash to your insurer. Keep records.
You do not have to solve everything at the scene. You only need to take the next safe step. A calm, organized process helps protect your health, your vehicle, and your ability to handle the claim fairly.
Comments